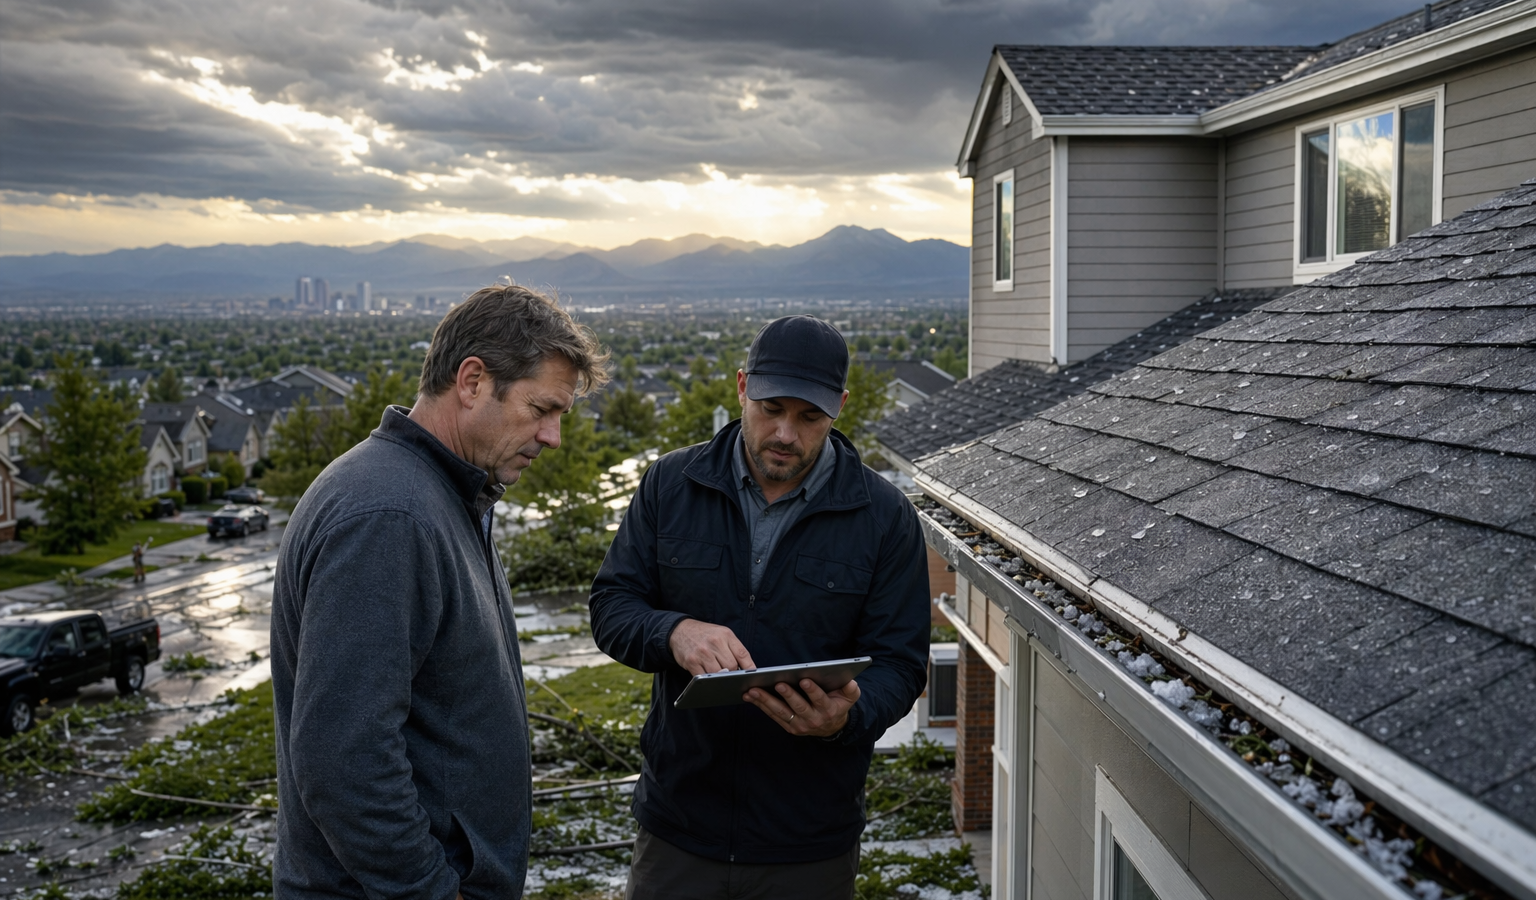
If a hailstorm just rolled through the Front Range, you’re probably wondering whether filing a roof claim will increase your premiums. The short answer: it can, but not always—and the details matter. Here’s a clear, Colorado-focused guide from AC INC. Roofing (Advanced Consulting, Inc.), a licensed and insured, 5-star-rated contractor serving the Denver metro area, Front Range, and Cheyenne, Wyoming.
The quick takeaway
- One weather-related claim typically won’t single-handedly spike your premium, but you could lose a claims-free discount.
- After big hail events, insurers often raise rates or adjust deductibles across entire ZIP codes—even for people who didn’t file.
- Multiple claims in a short period are more likely to increase premiums.
- Filing a claim for minor damage below your deductible can backfire if it’s recorded as a claim.
How insurers usually view roof claims in Colorado
Colorado is one of the nation’s most active hail markets. Insurers price risk based on both individual history and territory-wide losses. That means:
– Cause of loss matters: Weather-related (hail, wind, snow/ice) vs. wear-and-tear or maintenance issues.
– Frequency and severity: Two or more claims in 3–5 years often trigger surcharges.
– Territory performance: Big Front Range hailstorms can drive area-wide increases and higher wind/hail deductibles.
– Roof age and material: Older shingles and non-impact-resistant products tend to cost more to insure.
– Deductibles and discounts: A claims-free discount may drop off after a paid claim; some carriers also give credits for Class 4 impact-resistant shingles.
Weather claims vs. maintenance issues
- Weather-related losses (hail, wind) are generally considered “no-fault,” but they still affect the insurer’s overall costs, which can lead to territory-wide adjustments.
- Wear-and-tear, aging, or prior installation defects typically aren’t covered. Filing for non-covered issues can create a recorded claim without a payout—potentially removing discounts.
Will a single hail claim raise my rate?
- Maybe. You might see little to no change beyond losing a claims-free discount. However, your ZIP code could see increases after a major storm whether you filed or not.
- Large payouts, repeat claims, or short intervals between claims make premium increases more likely.
What about “zero-dollar” or below-deductible claims?
Some carriers still record these as claims, which can remove a claims-free discount. That’s why it’s smart to confirm damage and estimated costs before opening a claim.
How long do roof claims affect premiums?
Property claim history often follows you 5–7 years through industry reports like CLUE. Switching insurers won’t necessarily reset your record.
Steps to take before you file
- Schedule a professional inspection: AC INC. Roofing offers free roof inspections by HAAG-certified inspectors (we hold Master HAAG Certification—the first company in Colorado to reach Master level). We document functional hail or wind damage vs. cosmetic concerns.
- Compare findings to your deductible: If repairs are likely below deductible, consider paying out-of-pocket to preserve your claims-free status.
- Gather thorough documentation: Date-stamped photos, slope-by-slope damage maps, test squares, and moisture readings help insurers assess damage faster.
- Stabilize the roof: Address leaks quickly to prevent interior damage. Keep receipts for temporary mitigation.
- File a well-supported claim—if appropriate: AC INC. Roofing provides detailed reporting and meets on site to review findings with your adjuster. We’re experts in storm-damage evaluation, insurance advocacy, and providing thorough documentation for claims.
Ways to minimize future premium impact
- Choose impact-resistant materials: We install premium systems like Atlas impact-resistant shingles, metal, tile, and commercial membranes (TPO, EPDM, Modified Bitumen). Impact-resistant shingles can qualify for carrier discounts in many cases—check with your insurer.
- Consider fortified assemblies: As a Fortified Roofing Solutions certified contractor, we build roofs designed to withstand 130 mph winds, EF-2 tornadoes, and 2″ hail—helping reduce future loss exposure.
- Maintain proactively: Regular inspections after hail, snow, and wind events catch small issues early. Our team provides inspections, repairs, rejuvenation, siding, and gutter services to strengthen your building envelope.
- Optimize deductibles wisely: Higher wind/hail deductibles can lower premiums, but make sure they match your risk tolerance and reserve funds.
Common Colorado questions we hear
- Are cosmetic dents covered? Many policies exclude cosmetic-only metal damage; functional damage is key. We help document what’s functional vs. cosmetic.
- Will Class 4 shingles lower my bill? Often there’s a credit on the wind/hail portion, but amounts vary by carrier and ZIP. Ask your agent for specifics.
- Can I avoid a surcharge by switching insurers? Your claim history typically follows you; switching isn’t a guaranteed solution.
- Do HOA or multi-building claims work differently? Master policies and deductibles can be complex. We routinely assist property managers with thorough documentation across multiple buildings.
Why homeowners and property managers choose AC INC. Roofing
- Credentials that matter: Master HAAG Certification; Atlas Pro+ Platinum Certified (up to 50-year warranties); GAF Certified (System Plus warranties available); Directorii-certified (backed by up to $20,000 customer guarantee).
- Commercial and residential expertise: Inspections, repairs, replacements, rejuvenation, storm damage restoration, and insurance claims support.
- Premium materials: Atlas shingles, metal and tile systems, TPO, EPDM, Modified Bitumen, and fluid-applied coatings.
- Local, trusted, and insured: Based at 6145 Broadway, Suite 25, Denver, CO 80216. 5.0-star Google rating from our Colorado clients.
- Professional memberships: RSRA (invitation-only), CRA, NRCA, and APA.
Bottom line
Filing a roof claim doesn’t automatically raise your premiums, but it can remove discounts and contribute to territory-wide adjustments—especially after Front Range hailstorms. The smartest move is to verify damage and costs first, then file only when it makes financial sense.
Get the clarity you need from a team that handles Colorado hail and snow loads every season. Contact Us today.